TL;DR

Get bike and ride gear delivered free — and shop member deals
- Fast, free delivery on millions of items
- Access to Prime Big Deal Days deals on October 6–7
- Prime Video, Amazon Music and more included
Online attention has spiked around reporting on a Texas factory working to produce rare-earth magnets for EVs, an area where China dominates global supply. The surge in interest is confirmed, but the specific development driving it this week is not yet verified.
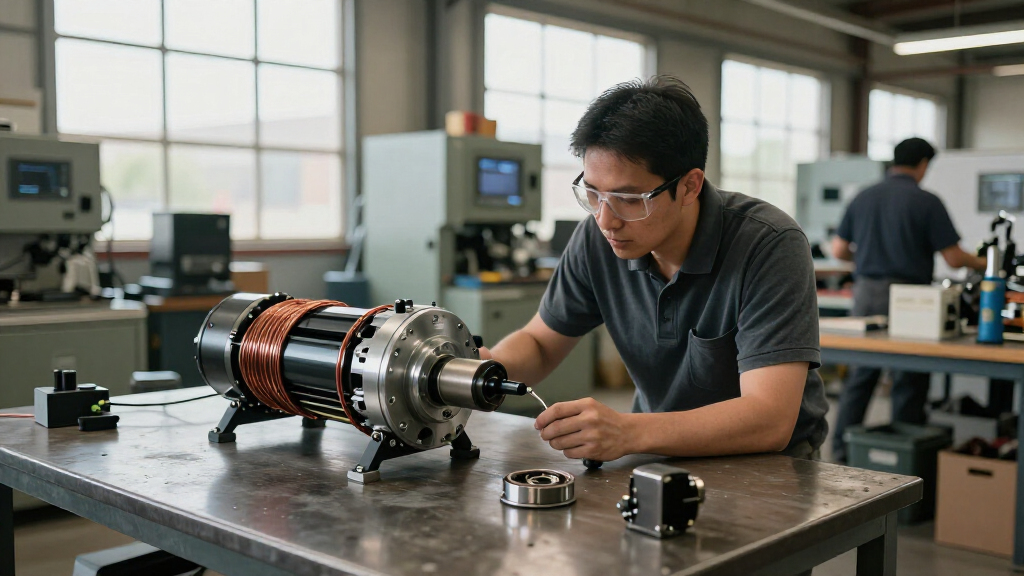
Reader and search interest has spiked in a story described as “Inside The Texas Factory Racing To Break China’s Grip On EV Magnets.” The subject is a Texas manufacturing facility working to produce the rare-earth permanent magnets that sit at the heart of electric vehicle motors — components the United States currently imports, overwhelmingly, from China and from Chinese-controlled supply chains. The topic itself is well established; what is not yet confirmed is the specific development — a new announcement, funding round, production milestone, or high-profile interview — that caused interest to surge at this moment.
The subject of the story is a real and long-standing industrial challenge, part of a broader race to break China’s grip on the EV supply chain. Modern EVs rely on neodymium-iron-boron (NdFeB) permanent magnets, which power the motors in most electric drivetrains. Producing them at commercial scale requires a supply chain that includes mining, separation, refining, alloying, and magnet fabrication — and China currently dominates nearly every stage of that chain. That dominance is a matter of long-established record, cited repeatedly by U.S. government agencies, industry analysts, and automakers.
In response, the United States has spent years pushing to rebuild domestic magnet production. Federal programs, including Department of Defense and Department of Energy funding, have supported several domestic magnet ventures, and Texas has emerged as a site for more than one such project because of its industrial base and port access. Automakers including General Motors have publicly announced agreements with domestic magnet developers to supply future EV production — a fact that predates the current wave of attention.
What is confirmed right now is the spike in coverage and search interest around the Texas factory framing. What is unconfirmed is the trigger: whether the renewed attention reflects a fresh funding announcement, a production start, a journalist visit published this week, a policy development in Washington, or simply a wave of aggregator-driven recirculation of earlier reporting. Readers should treat any specific new claims — output figures, hiring numbers, delivery contracts — as unverified until they appear in an attributable primary statement from the company or a government agency.
Why Magnet Independence Matters for EV Buyers
Rare-earth magnets are a chokepoint in the EV supply chain. Even as battery plants multiply across North America, the motors that convert electrical energy into motion still depend on magnet materials whose refining is concentrated in China. Recent geopolitical tension has made this concrete: Chinese export controls on rare-earth materials and magnets, imposed in recent years, have disrupted automakers and suppliers worldwide and demonstrated how quickly a single policy decision can stall production lines.
For consumers, the practical stakes are supply stability and cost. A shortage of finished magnets can slow vehicle assembly and raise prices, regardless of how many battery cells are available. For the broader economy, domestic magnet production is tied to industrial policy, jobs, and national security arguments that have drawn bipartisan political support. That is why a single factory in Texas can attract outsized attention: each new magnet plant represents a measurable reduction in import dependence.
How the U.S. Lost and Is Rebuilding Magnet Making
The United States was once a leader in rare-earth processing but ceded that position over decades as lower-cost Chinese production expanded. By the 2010s, China controlled the large majority of global rare-earth mining, separation capacity, and magnet fabrication, a concentration documented by the International Energy Agency and the U.S. Geological Survey in their recurring market reports.
Rebuilding the domestic chain has been gradual. Recent years brought federal Defense Production Act funding, tax-credit support for critical minerals under major industrial legislation, and several announced magnet plants in Texas and other states, some tied to supply agreements with major automakers. Timelines for these projects have often slipped relative to initial announcements, which is common in capital-heavy processing industries. That history is why each milestone at facilities like the Texas plant draws close attention from industry watchers.
What the Surge Doesn’t Yet Tell Us
The trigger for the current spike is unconfirmed. It is not clear whether the underlying article is new reporting, a republished feature, or a summary of previously disclosed developments. The identity of the specific factory, its owner, its production capacity, its funding status, and its delivery timeline all remain unverified from the available information.
Additional open questions include whether any automaker supply agreement accompanies the coverage, whether federal agencies have made a related award or regulatory decision, and whether China’s export-control policy has changed in a way that renewed attention to the topic. Claims circulating on social media about the plant’s output or significance should be treated cautiously until a named company or agency confirms them.
Milestones That Would Confirm the Story
Watch for primary-source confirmation: a named company press release, a Department of Energy or Defense funding notice, or a filing disclosing production timelines. Additional markers include announcements of automaker offtake agreements, hiring surges at the Texas site, or first-shipment reports from the facility.
Policy developments could also shape the story, including any change in Chinese export licensing for rare-earth magnets or new U.S. tariff or credit measures affecting critical minerals. Each of these would independently move both the industry and the public interest now concentrated on this single factory.
Key Questions
Why do EVs need rare-earth magnets?
Most electric vehicle motors use neodymium-based permanent magnets to generate torque efficiently. They are compact and powerful, which helps extend driving range, but their raw materials and refining are heavily concentrated in China.
Is the Texas factory already producing magnets?
That is not confirmed from the available information. The identity of the facility and its current production status are unverified; readers should look for a company statement or government notice before treating any output claims as fact.
How dependent is the U.S. on China for these magnets?
Extremely. Long-established analyses from agencies such as the U.S. Geological Survey and the International Energy Agency show China dominating rare-earth mining, separation, and finished-magnet production, which is why this factory’s success would matter.
Why is interest in this story spiking now?
Coverage and search volume have clearly increased, but the specific trigger is unconfirmed. Possible drivers include new reporting, a funding or production milestone, or heightened attention after Chinese export controls disrupted auto supply chains.
Could domestic magnet production lower EV prices?
It could reduce supply-chain risk and some costs over time, but magnet plants take years to reach scale. Near-term prices depend more on materials markets, tariffs, and overall EV demand than on any single facility.
Source: rss
Fall Picks
fall essentials
As an affiliate, we earn on qualifying purchases.